Section 263A UNICAP Small Business Exemption Study
Built, renovated, or improved a property since 2018? Part of that cost may be deductible now instead of over decades.
What is a 263A UNICAP exemption study?
Section 263A (UNICAP) normally requires businesses to capitalize a project’s indirect costs, like design fees, supervision, taxes, and interest, into the property’s basis. The Tax Cuts and Jobs Act exempted taxpayers under a gross receipts threshold. If you qualify, those costs may be deductible sooner. Our study confirms eligibility, quantifies the costs, and documents it for your CPA.
Who it’s for
- Owners and developers with a new build, renovation, expansion, or tenant improvements since 2018
- Businesses that care about cash flow now, not basis later
- CPAs who want a documented analysis for a client
How it works
Screen eligibility
We review the project, the entity, and the timeline to see whether it is worth a closer look.
Quantify the opportunity
We analyze construction and indirect costs to estimate the amount that could be affected.
Document it
We prepare CPA-ready documentation of costs, timelines, and methodology.
Hand off to your CPA
Your CPA reviews the study, decides the filing position, and implements any required method change.
What you get
- Eligibility screening
- Breakdown of eligible indirect costs
- Documentation package for your CPA
- Support while your CPA implements it
What we’ll ask for
- Final construction cost report or job-cost ledger
- Contractor draws or pay applications
- Project dates (start, completion, placed-in-service)
- Ownership and entity information
- Your CPA’s contact information
Other services
Missing records? Tell us what you have and we’ll help with the rest.
Industries we serve
We provide 263A / UNICAP Exemption Study for:
Example projects
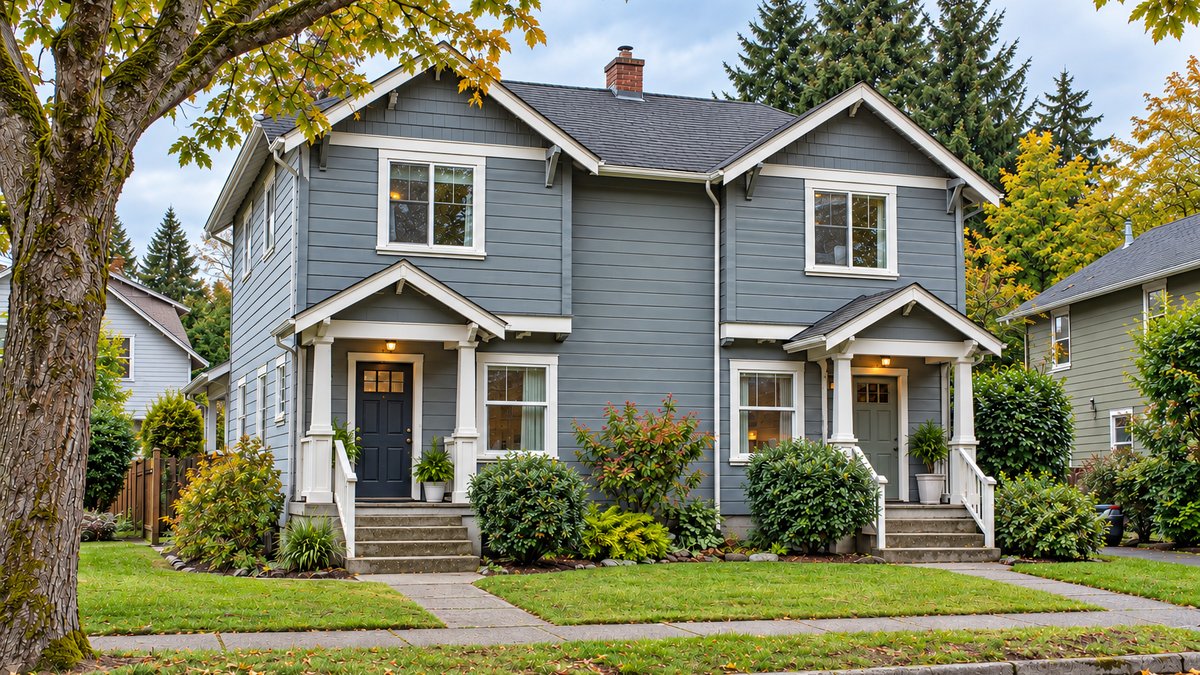
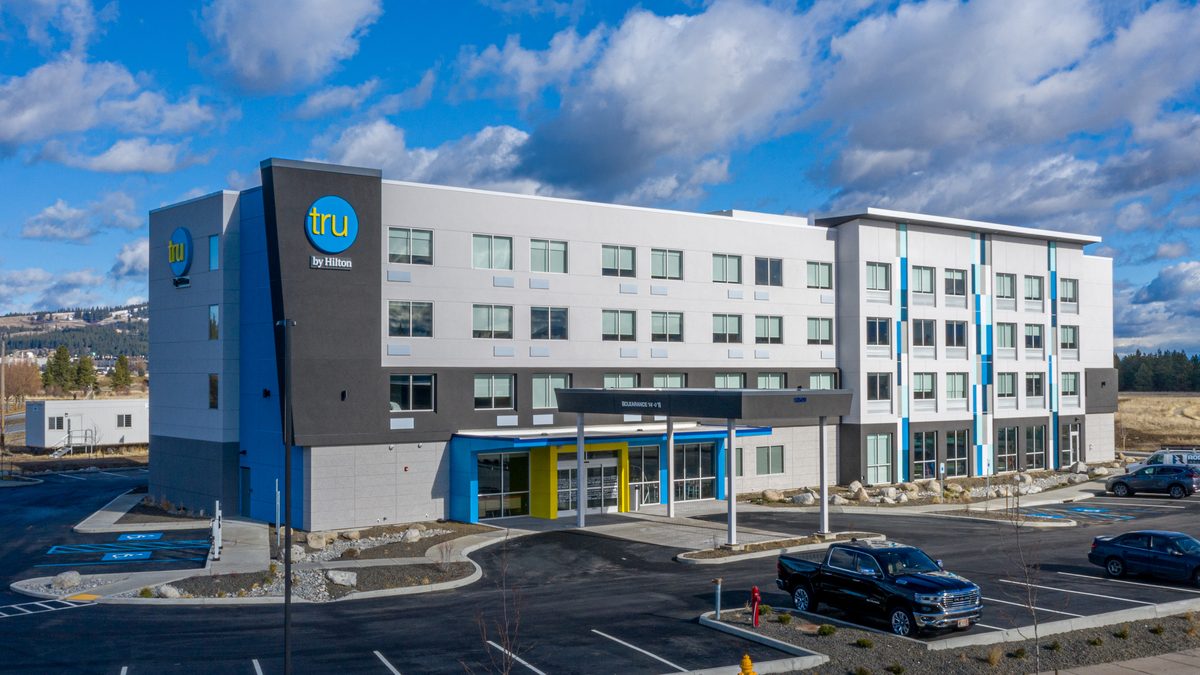
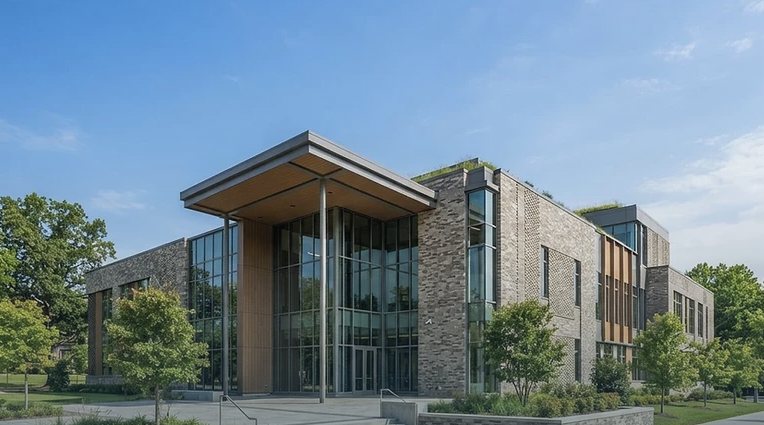
Results shown are past client results and are not a guarantee of future outcomes. Benefits are subject to qualification requirements and are tax-year dependent. Your CPA or EA remains the ultimate filing authority.
Common questions
Who decides whether to take the position?
Your CPA and the taxpayer. We provide decision support and documentation; we do not prepare returns or provide legal advice.
Can this apply to projects from prior years?
Sometimes. Depending on the facts, prior-year projects may be addressed through an accounting method change that your CPA files. We help determine whether it is worth pursuing.

See what your project could save.
Try the free calculator in about two minutes, or talk to our team.
Call (801) 899-9454